Skip to content
All bites
TaxesInfographic

Old vs New Tax Regime: The 60-Second Comparison

Lower tax rates or more deductions? One visual card to understand both income-tax regimes and the simple question that helps you pick.

24 Sept 20261 min read
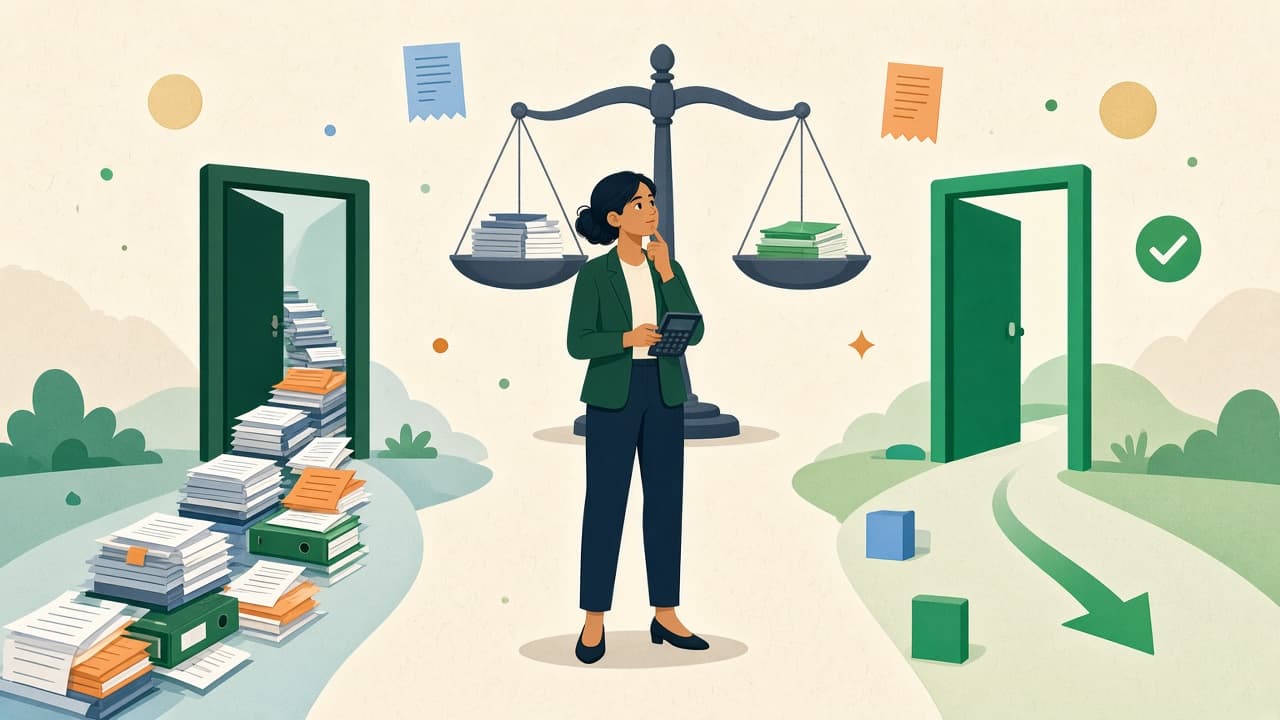
A young professional with a calculator stands between a path piled with receipts and a simple open path, under a balance scale

Every year, salaried Indians face the same question from HR: "Old regime or new regime?" Here's the difference in one card, based on the rates announced in Union Budget 2025.

Old Regime

New Regime

Tax rates
Higher slab rates (up to 30% above ₹10 lakh)
Lower rates, more slabs (30% only above ₹24 lakh)
Zero tax up to
₹5 lakh taxable income
₹12 lakh taxable income (₹12.75 lakh for salaried)
Standard deduction
₹50,000
₹75,000
Deductions (PPF, ELSS, insurance, HRA, home loan)
Allowed — can reduce taxable income a lot
Mostly not allowed
Paperwork
Proofs and investment declarations needed
Simple — very little to track
Default option
Must choose it actively
Yes, applies automatically

The one question to ask yourself

Animation: a balance scale tips between the old regime with many deductions and the new regime with lower rates.OLD · Deductions%NEW · Low ratesWhich saves more?
Watch: deductions vs lower rates

How much do you claim in deductions?

If your total deductions are large (HRA, home loan interest, 80C-type investments, health insurance), the old regime may still win. If not, the new regime is usually simpler and cheaper.

Quick rules of thumb

  • Just started working, no big deductions? The new regime is usually better.
  • Paying rent in a big city, have a home loan, and invest for tax saving? Calculate both — the old regime might save more.
  • Salaried? You can usually pick a different regime each year when filing your return.

दर वर्षी नोकरदार भारतीयांना HR कडून तोच प्रश्न येतो: "जुनी पद्धत की नवी?" युनियन बजेट २०२५ मध्ये जाहीर झालेल्या दरांनुसार फरक एका कार्डात.

जुनी पद्धत

नवी पद्धत

टॅक्स दर
जास्त स्लॅब दर (₹१० लाखांवर ३०% पर्यंत)
कमी दर, जास्त स्लॅब (३०% फक्त ₹२४ लाखांवर)
शून्य टॅक्स पर्यंत
₹५ लाख करपात्र उत्पन्न
₹१२ लाख करपात्र उत्पन्न (नोकरदारांसाठी ₹१२.७५ लाख)
स्टँडर्ड डिडक्शन
₹५०,०००
₹७५,०००
सवलती (PPF, ELSS, विमा, HRA, घरकर्ज)
मिळतात — करपात्र उत्पन्न खूप कमी होऊ शकतं
बहुतेक मिळत नाहीत
कागदपत्रं
पुरावे आणि गुंतवणूक घोषणा लागतात
सोपं — फारसं ट्रॅक करायचं नसतं
डीफॉल्ट पर्याय
स्वतःहून निवडावी लागते
हो, आपोआप लागू होते

स्वतःला विचारा एकच प्रश्न

Animation: a balance scale tips between the old regime with many deductions and the new regime with lower rates.OLD · Deductions%NEW · Low ratesWhich saves more?
Watch: deductions vs lower rates

तुम्ही किती सवलती क्लेम करता?

HRA, घरकर्जाचा व्याज, ८०C प्रकारची गुंतवणूक, आरोग्य विमा यांसारख्या सवलती जास्त असतील तर जुनी पद्धत अजूनही फायदेशीर ठरू शकते. नाहीतर नवी पद्धत सहसा सोपी आणि स्वस्त असते.

लगेच लक्षात ठेवायचे नियम

  • नुकतीच नोकरी सुरू, मोठ्या सवलती नाहीत? नवी पद्धत सहसा चांगली.
  • मोठ्या शहरात भाडं, घरकर्ज, आणि टॅक्स सेव्हिंग गुंतवणूक? दोन्ही मोजून पाहा — जुन्यात जास्त बचत होऊ शकते.
  • नोकरदार? रिटर्न भरताना साधारणपणे दर वर्षी वेगळी पद्धत निवडता येते.

Found this useful?

Forward it to one person who needs it today — a parent, a friend, a colleague.
Keep learning

A granddaughter warns her grandfather about a suspicious payment request on a phone, with warning and safety icons floating around them
3-Step Carousel
Scams & Cyber Safety

Never Enter Your UPI PIN to Receive Money

Scammers send "collect requests" that look like you're receiving cash. Here's the 3-step rule that keeps your bank account safe — forever.

  • #CyberSafety
  • #UPI
  • #ScamAlert
3 slides
A grandfather and granddaughter sit under a big mango tree, beside a row of saplings growing bigger from left to right
Story
SIPs & Mutual Funds

The Mango Tree Story: How a SIP Grows Your Money

Dadaji planted one small mango sapling every month. Twenty years later, his orchard explained SIPs and compounding better than any textbook.

  • #SIP
  • #Compounding
  • #MutualFunds
  • #InvestingBasics
2 min read